Field Notes
Dispatches on climate risk and real estate.
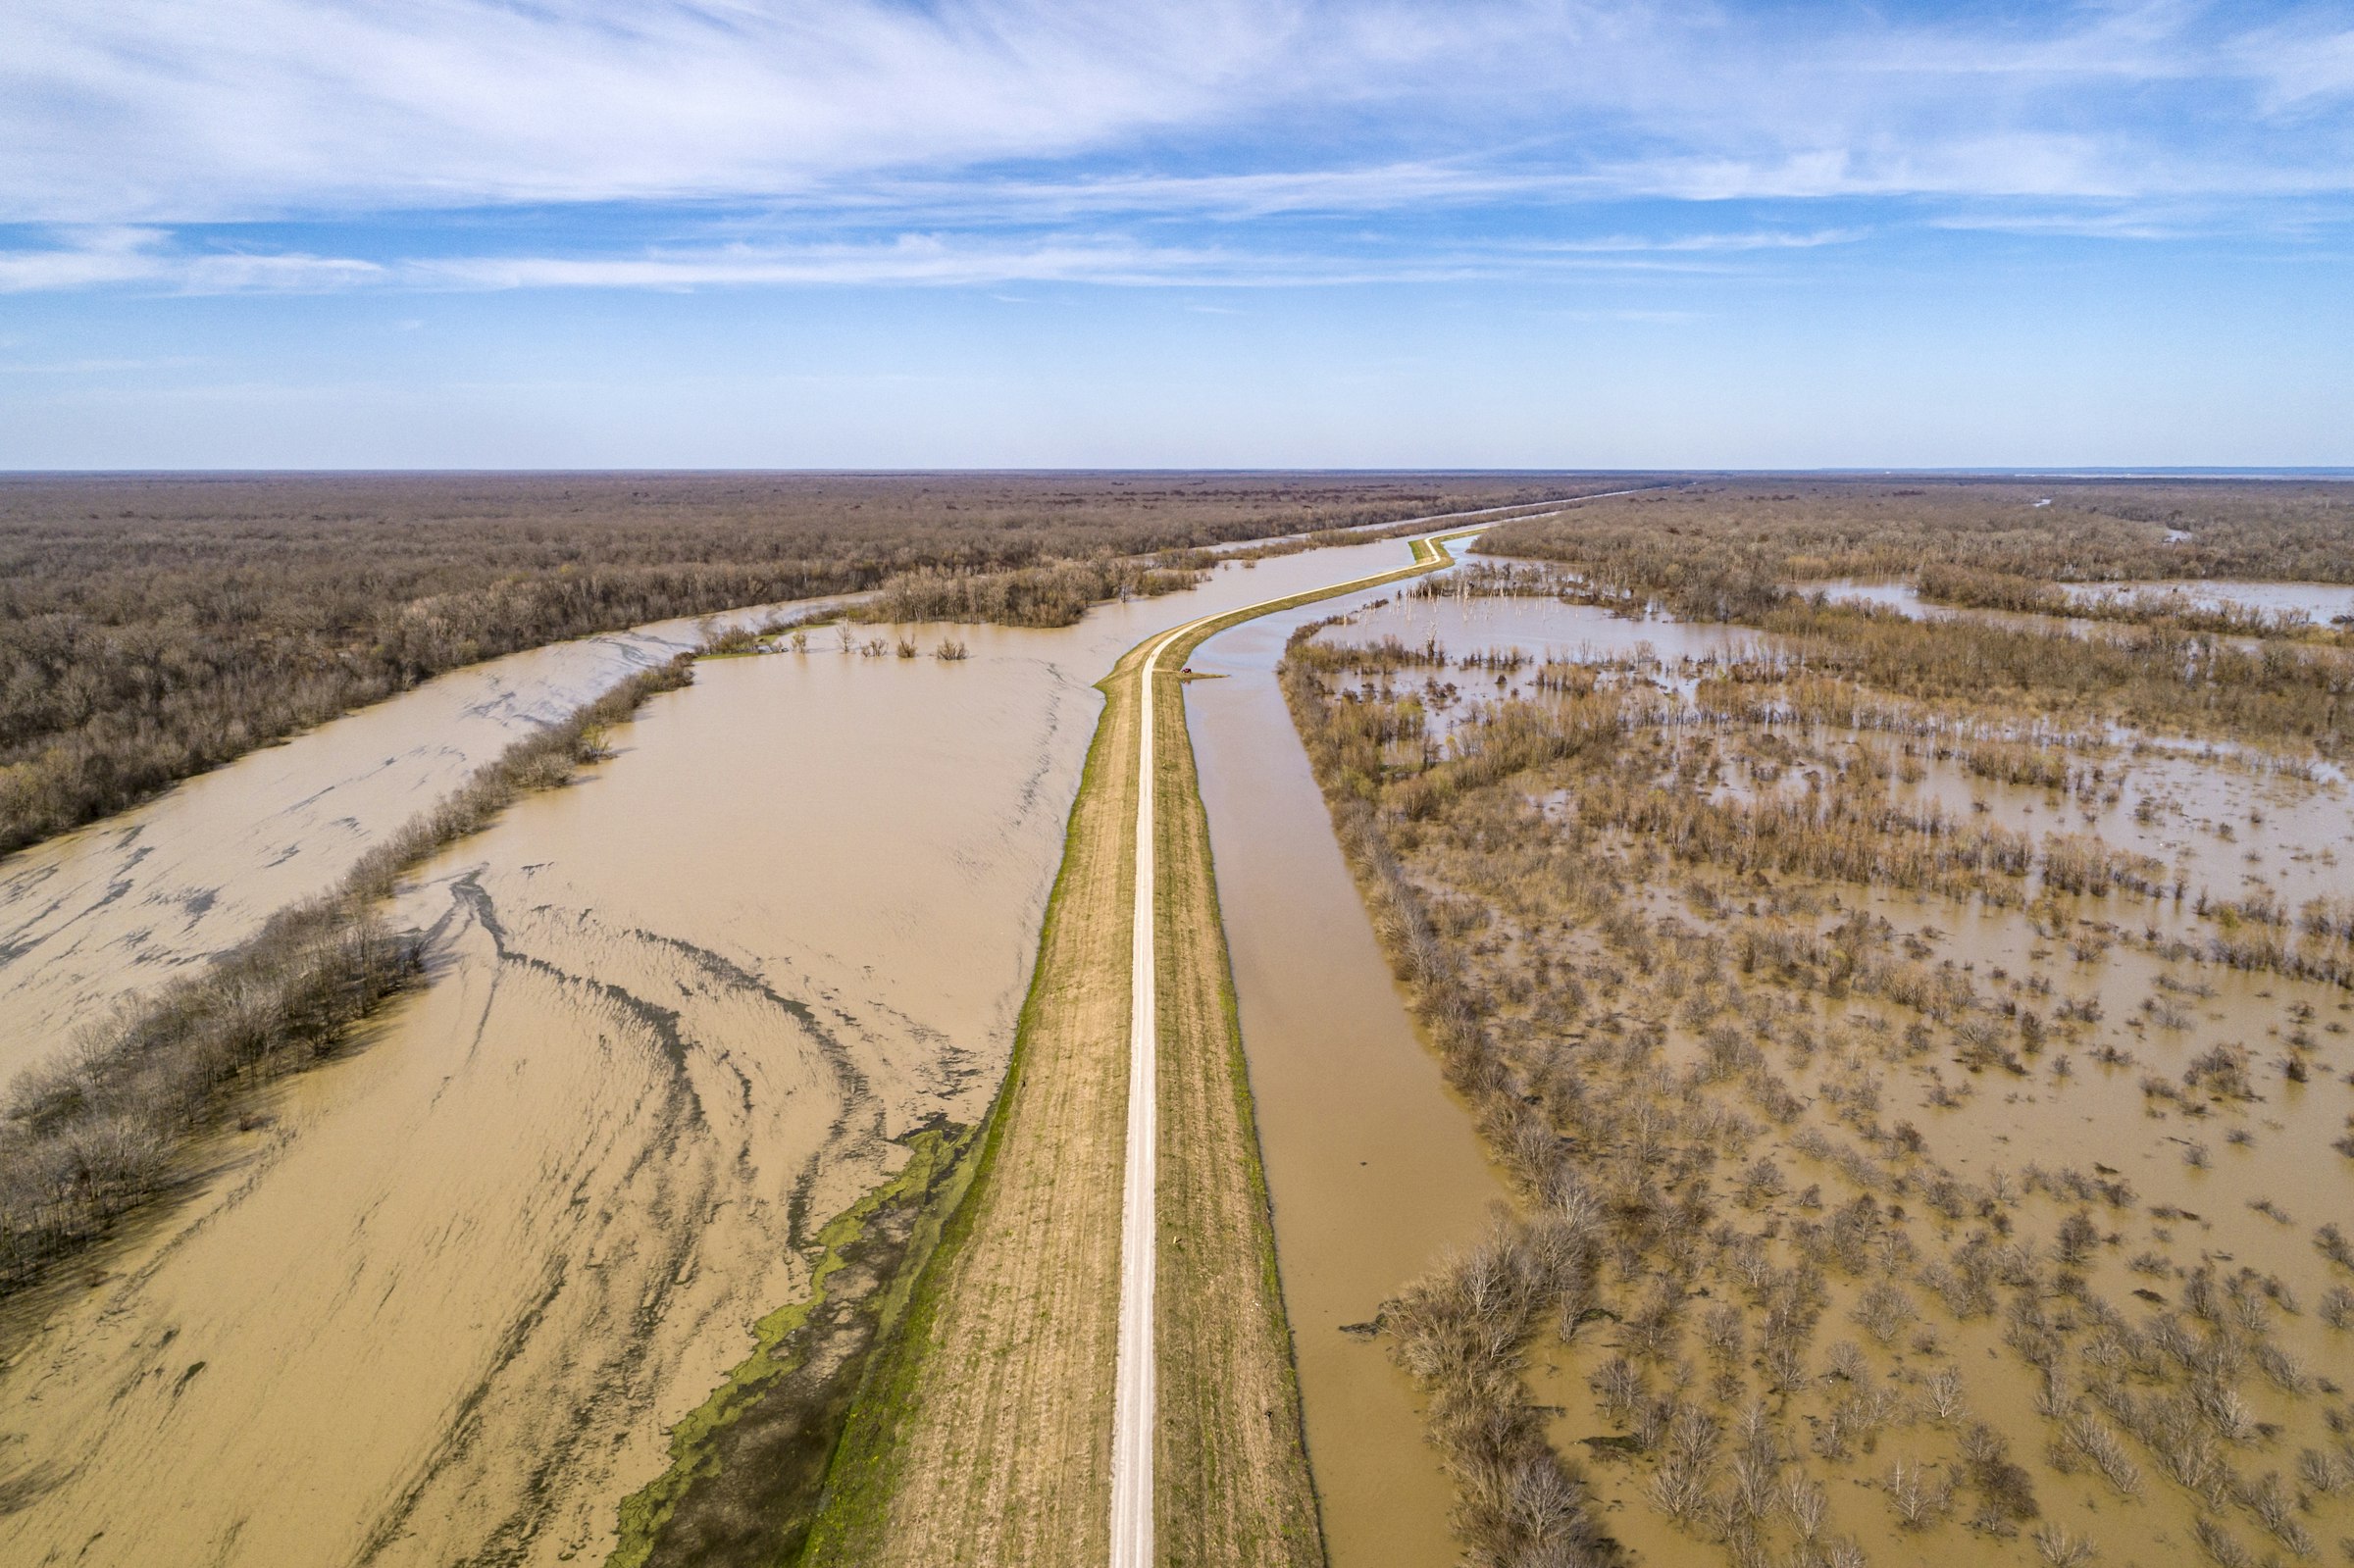
The Risk Under the House
America's thirty-year fixed mortgage works because the government stands behind roughly half of all home loans — and the fee for that guarantee is the same whether the house sits on a ridge or in a floodway. The Congressional Budget Office prices the difference at hundreds of millions of dollars a year, paid by the public.
What You Can Still Do to Lower Fire Premiums
California's insurer of last resort now itemizes twelve wildfire hardening discounts, worth up to 16.4 percent of the wildfire share of a premium. Behind that price list is a 2022 regulation that split a home's fire risk into two parts: where the house sits, and what its owner has done about it. Only one of those is fixed.
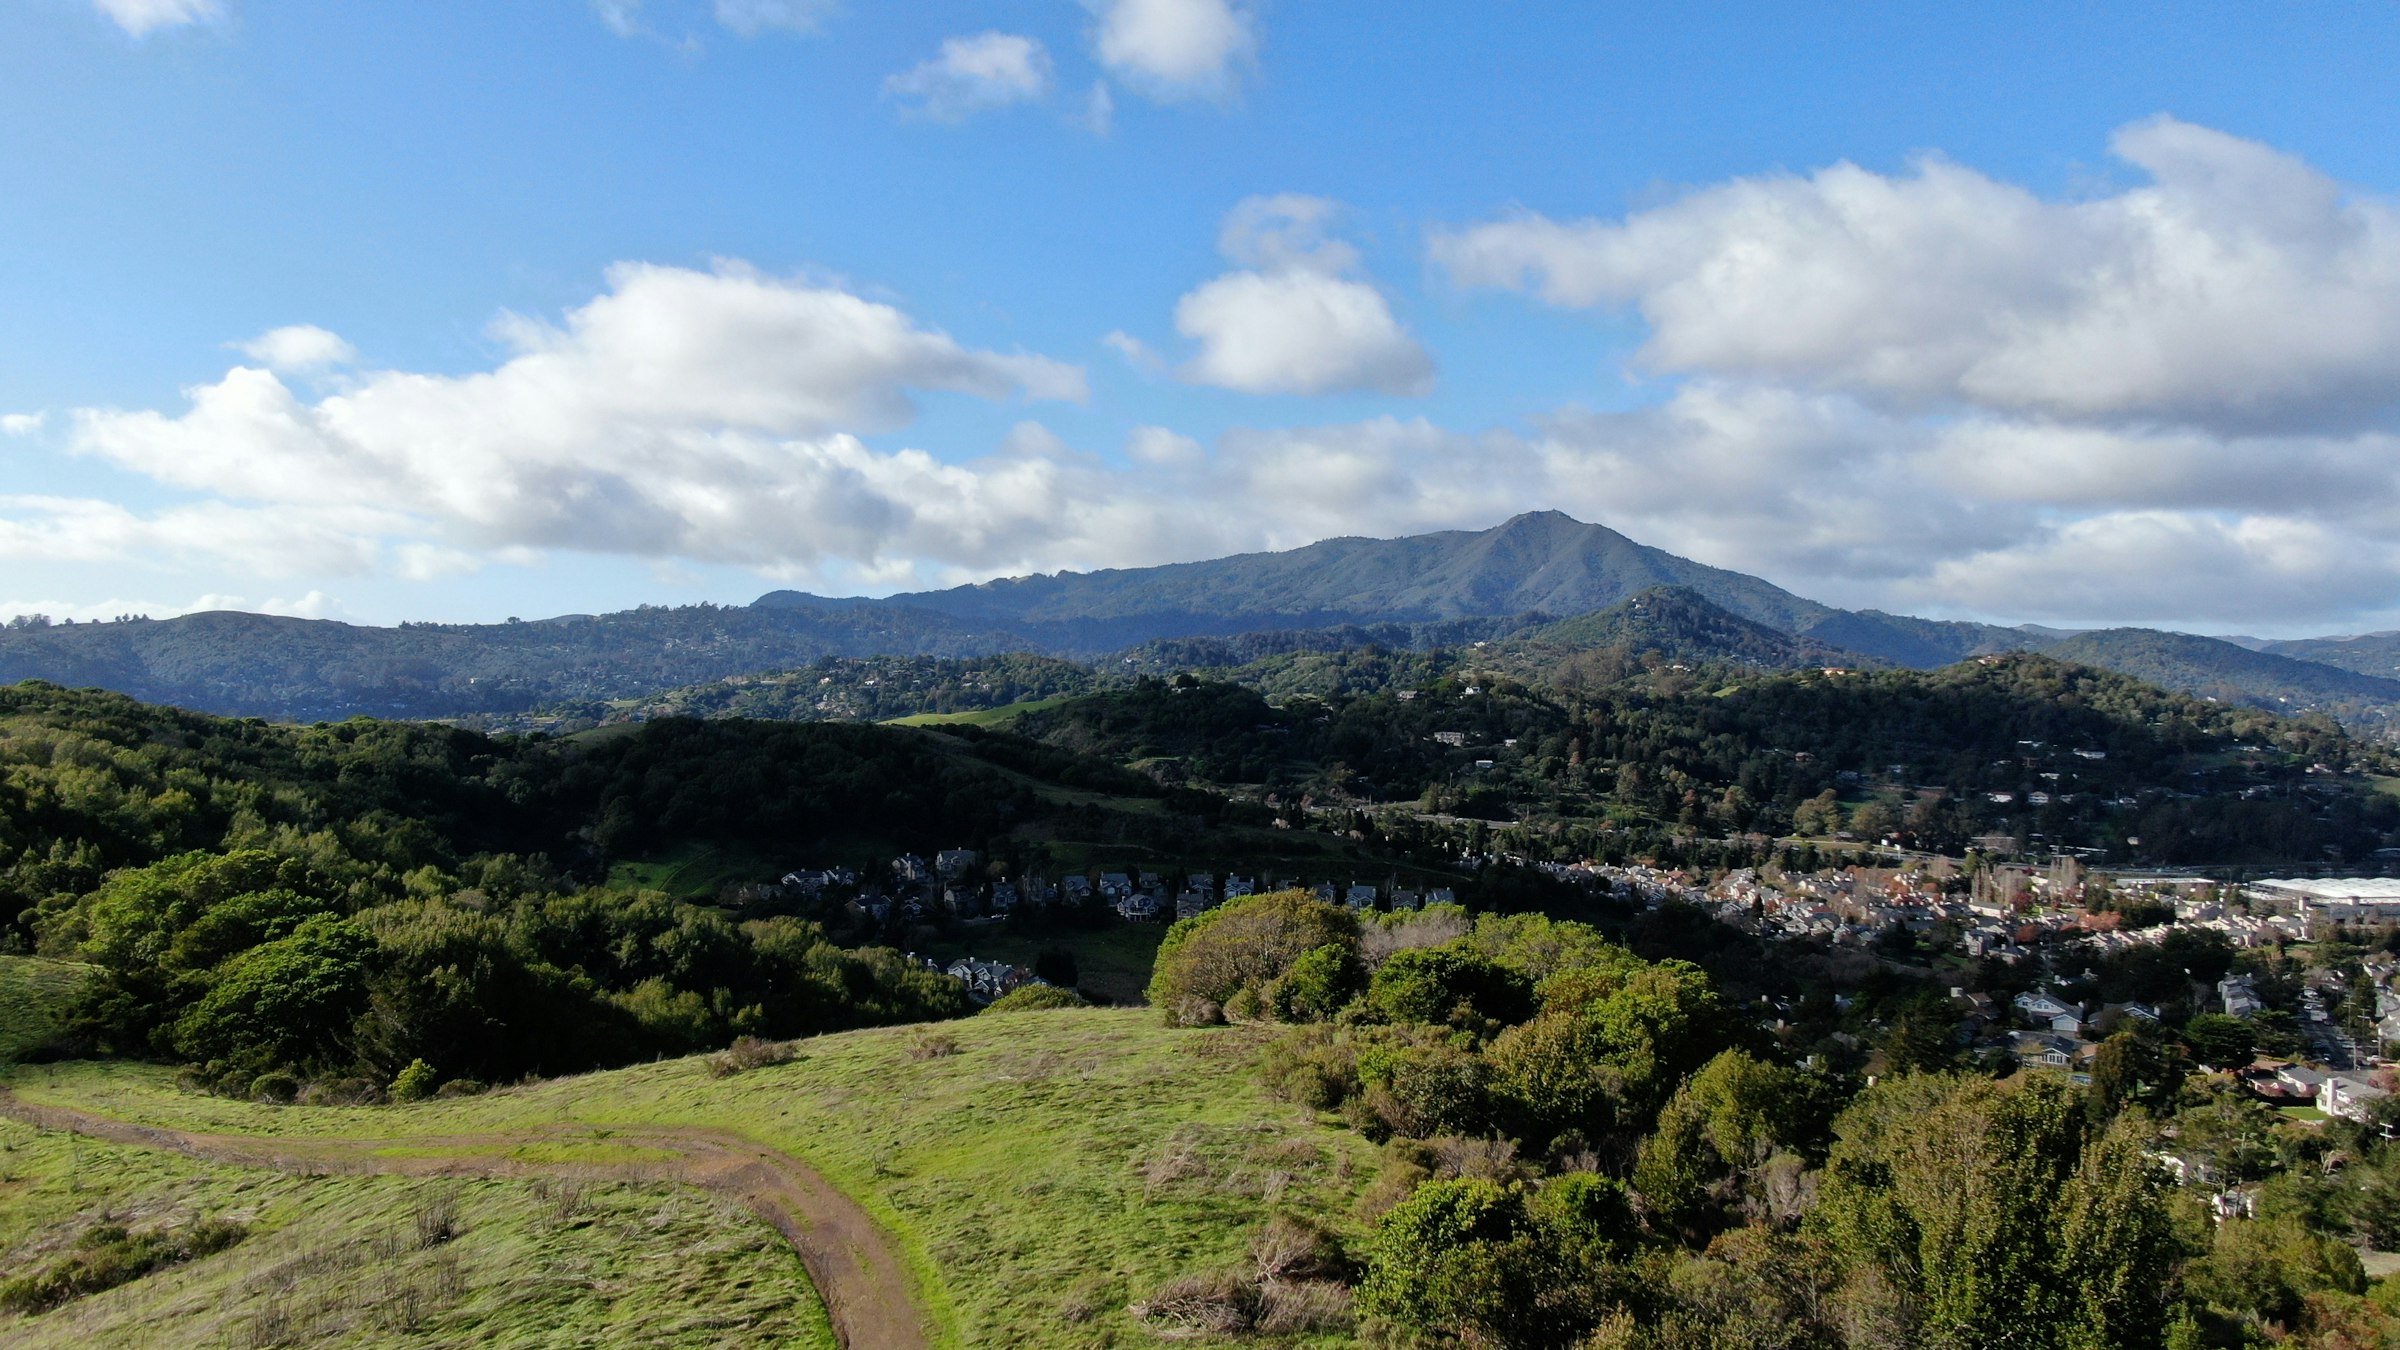
The Discount You Can't Earn Alone
Marin County had nine recognized Firewise sites in 2017. It has about ninety now. Behind that curve is a regulation that made one neighbor's brush clearing worth money to the house next door — and turned a favor between neighbors into an underwriting fact.
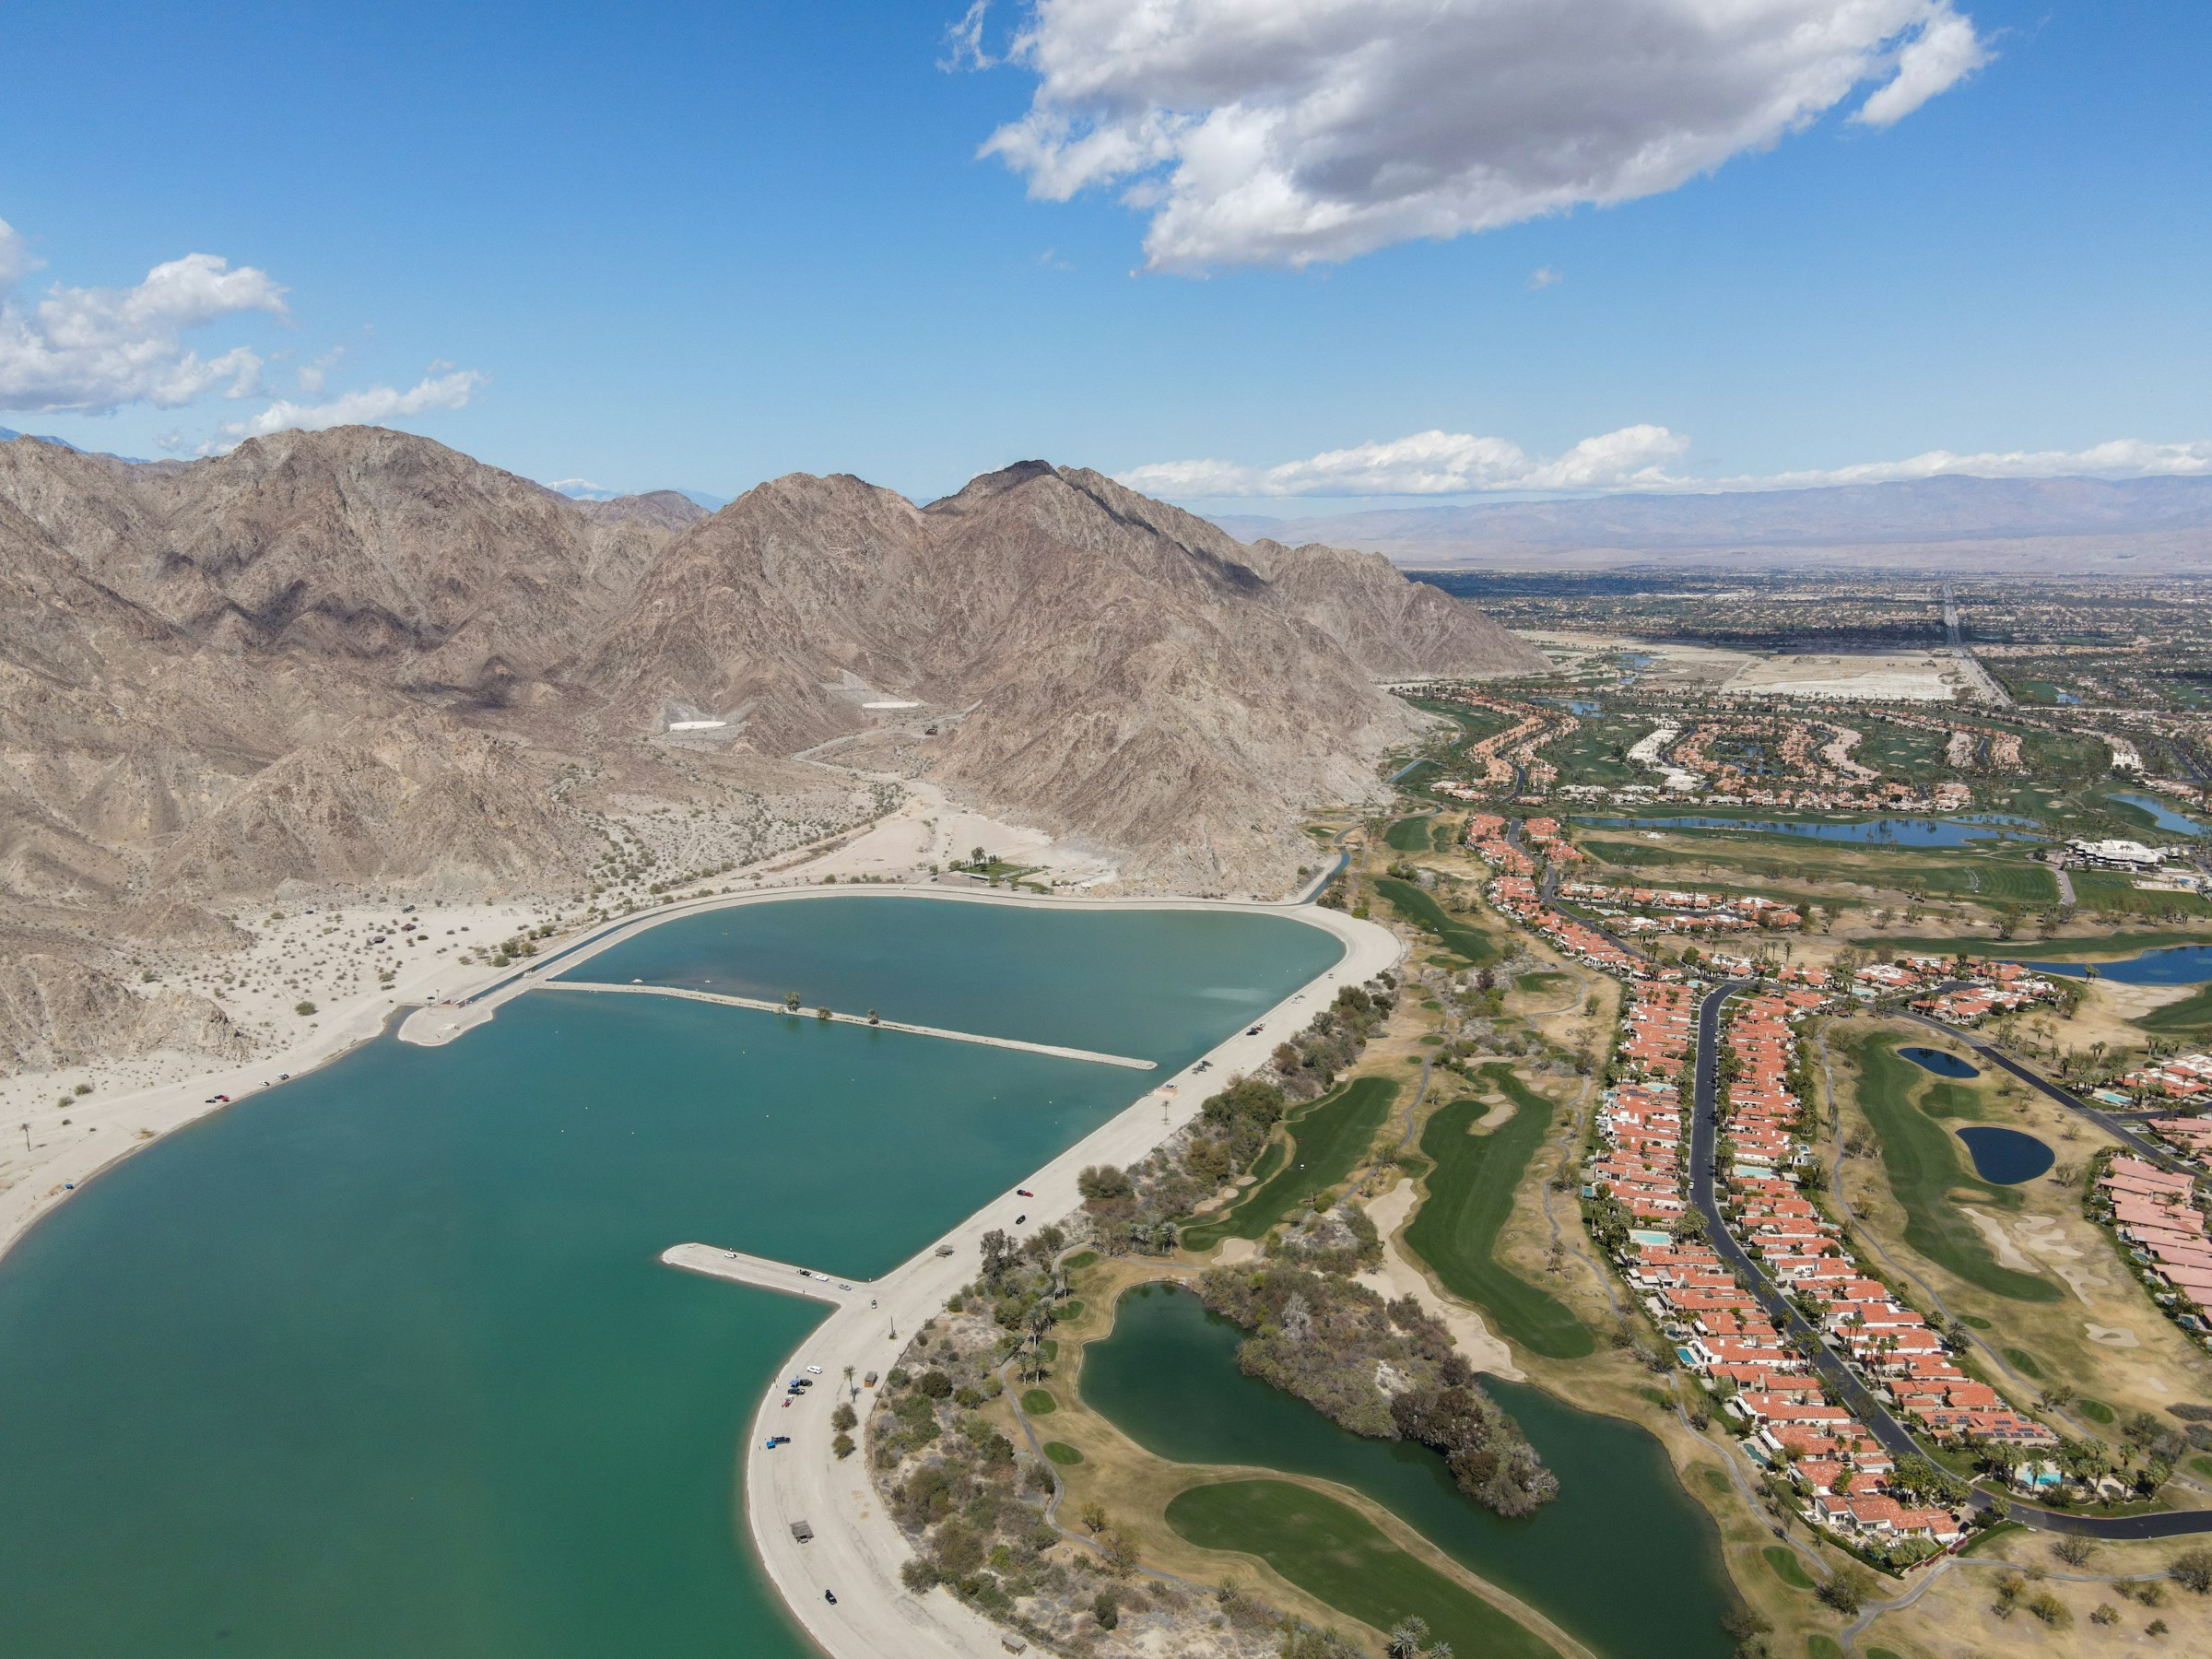
The House Was Never the Scarce Part
In October 2025, a signature on a water designation — the first of its kind in the Phoenix metro in 25 years — cleared the way for 60,000 homes. Not a housing bill; a water approval. That's the tell about how the desert grows now.
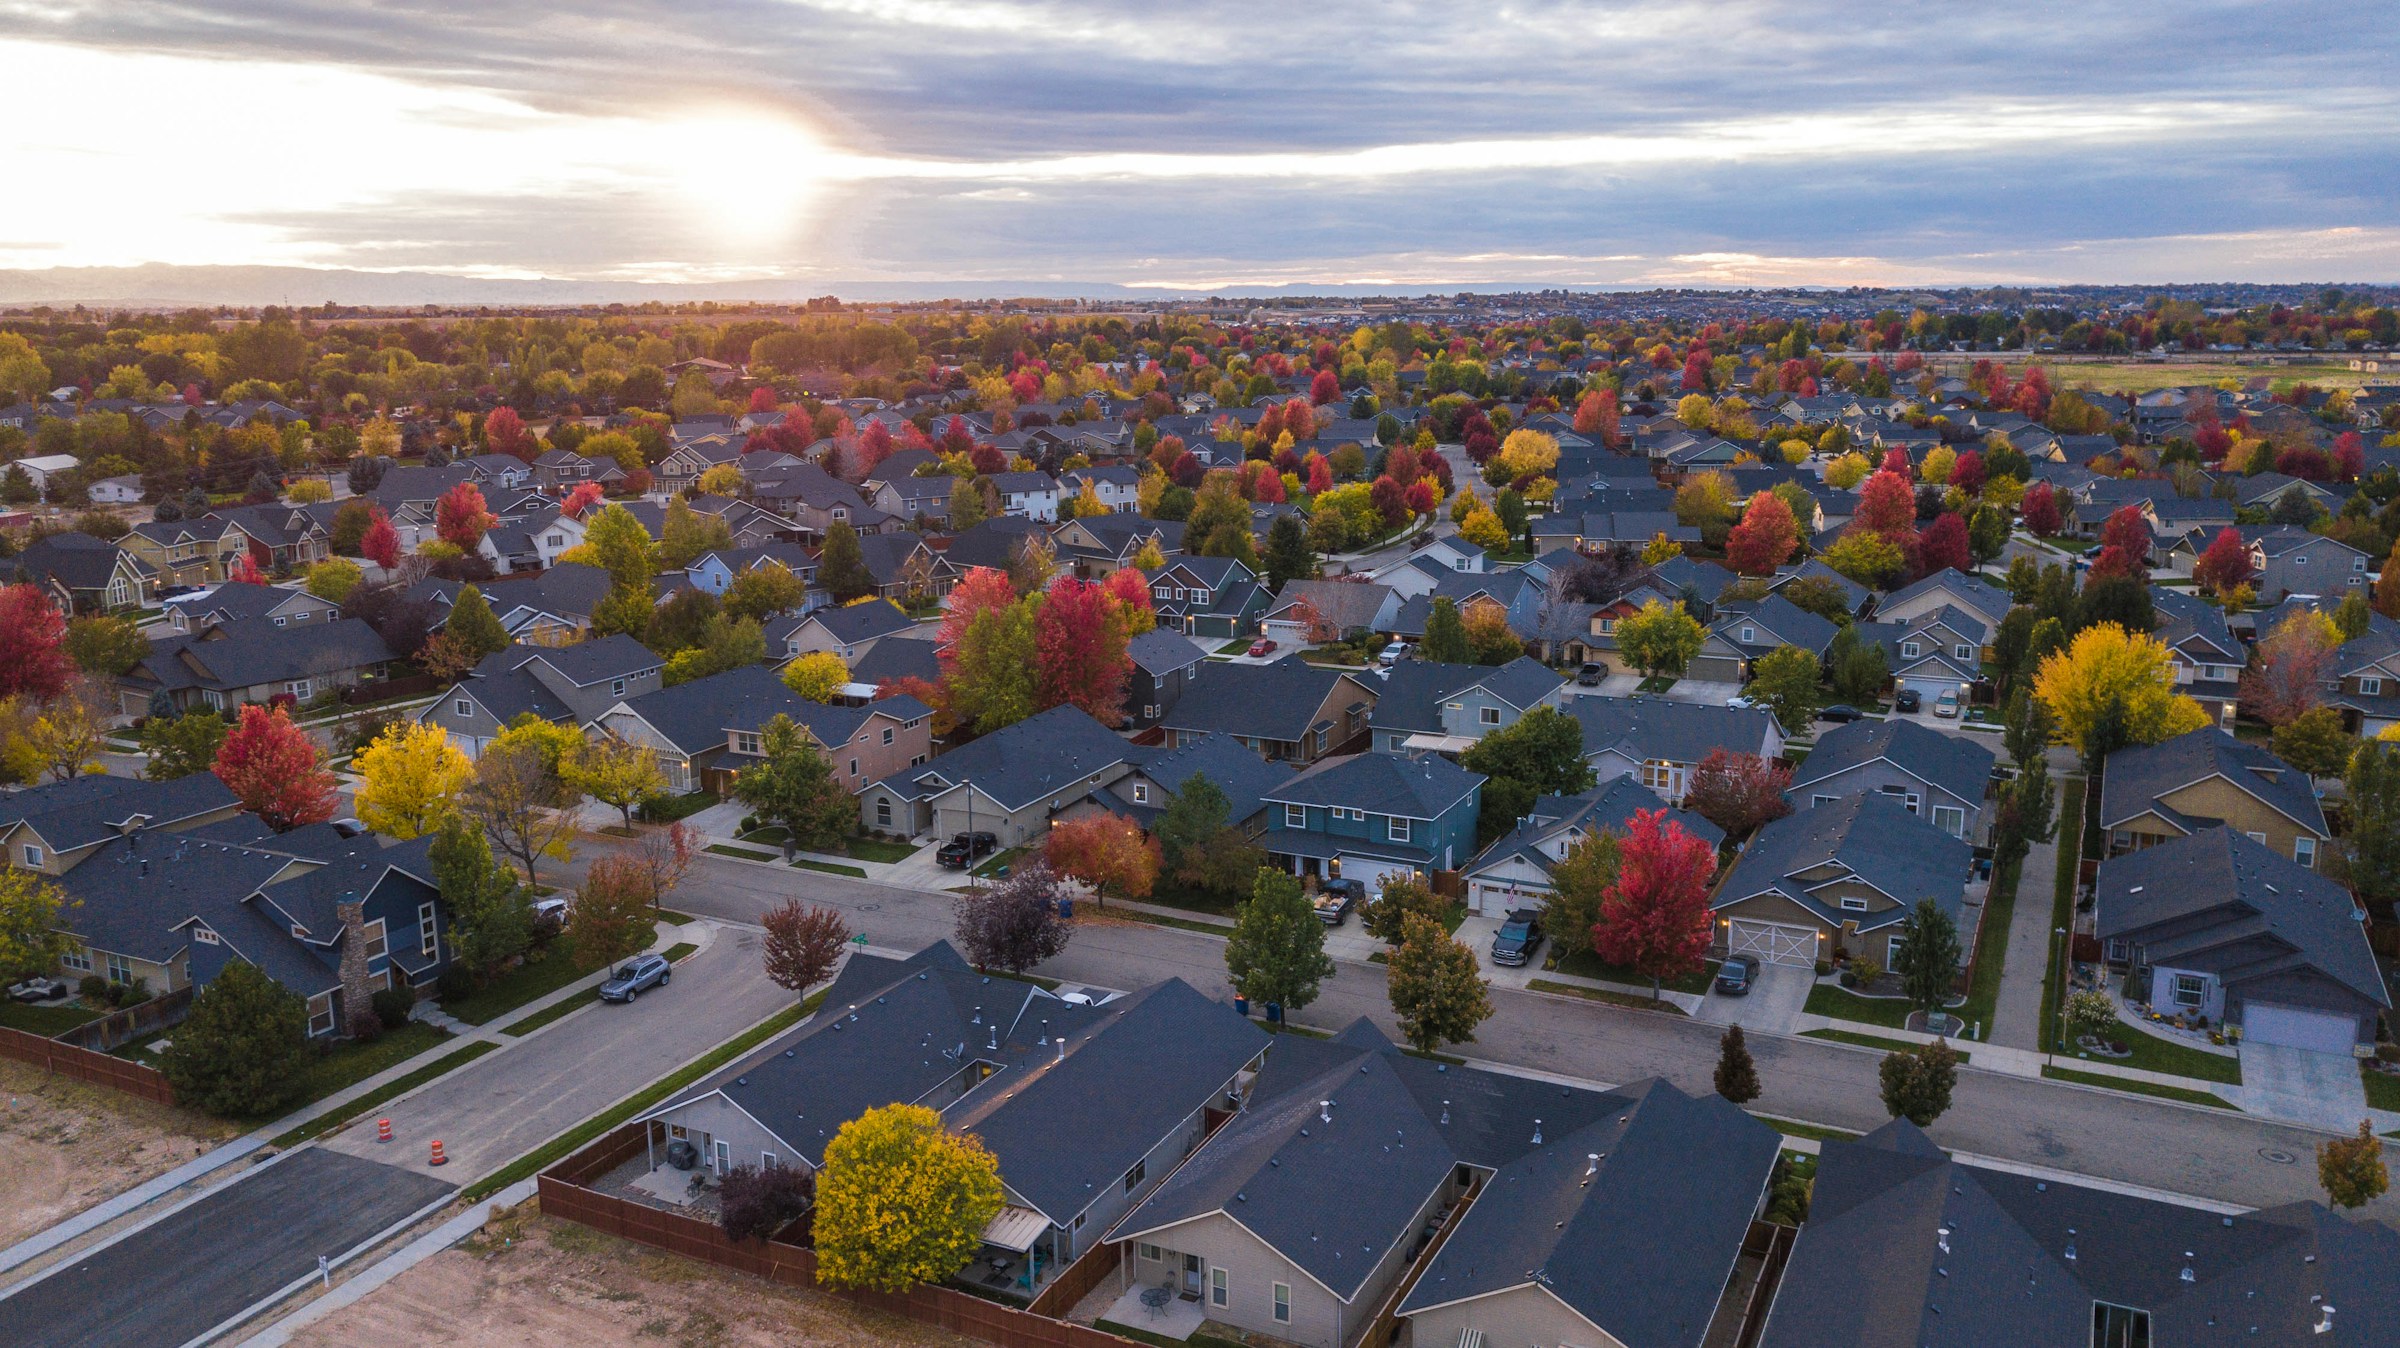
The Fire Was in Los Angeles. The Bill Is on Your Policy.
A homeowner miles from any wildfire is helping pay for the homes that burned in Los Angeles in January 2025. The FAIR Plan's $1 billion assessment worked exactly as designed — and the design now includes a line on ordinary policies, no matter how safe the address.
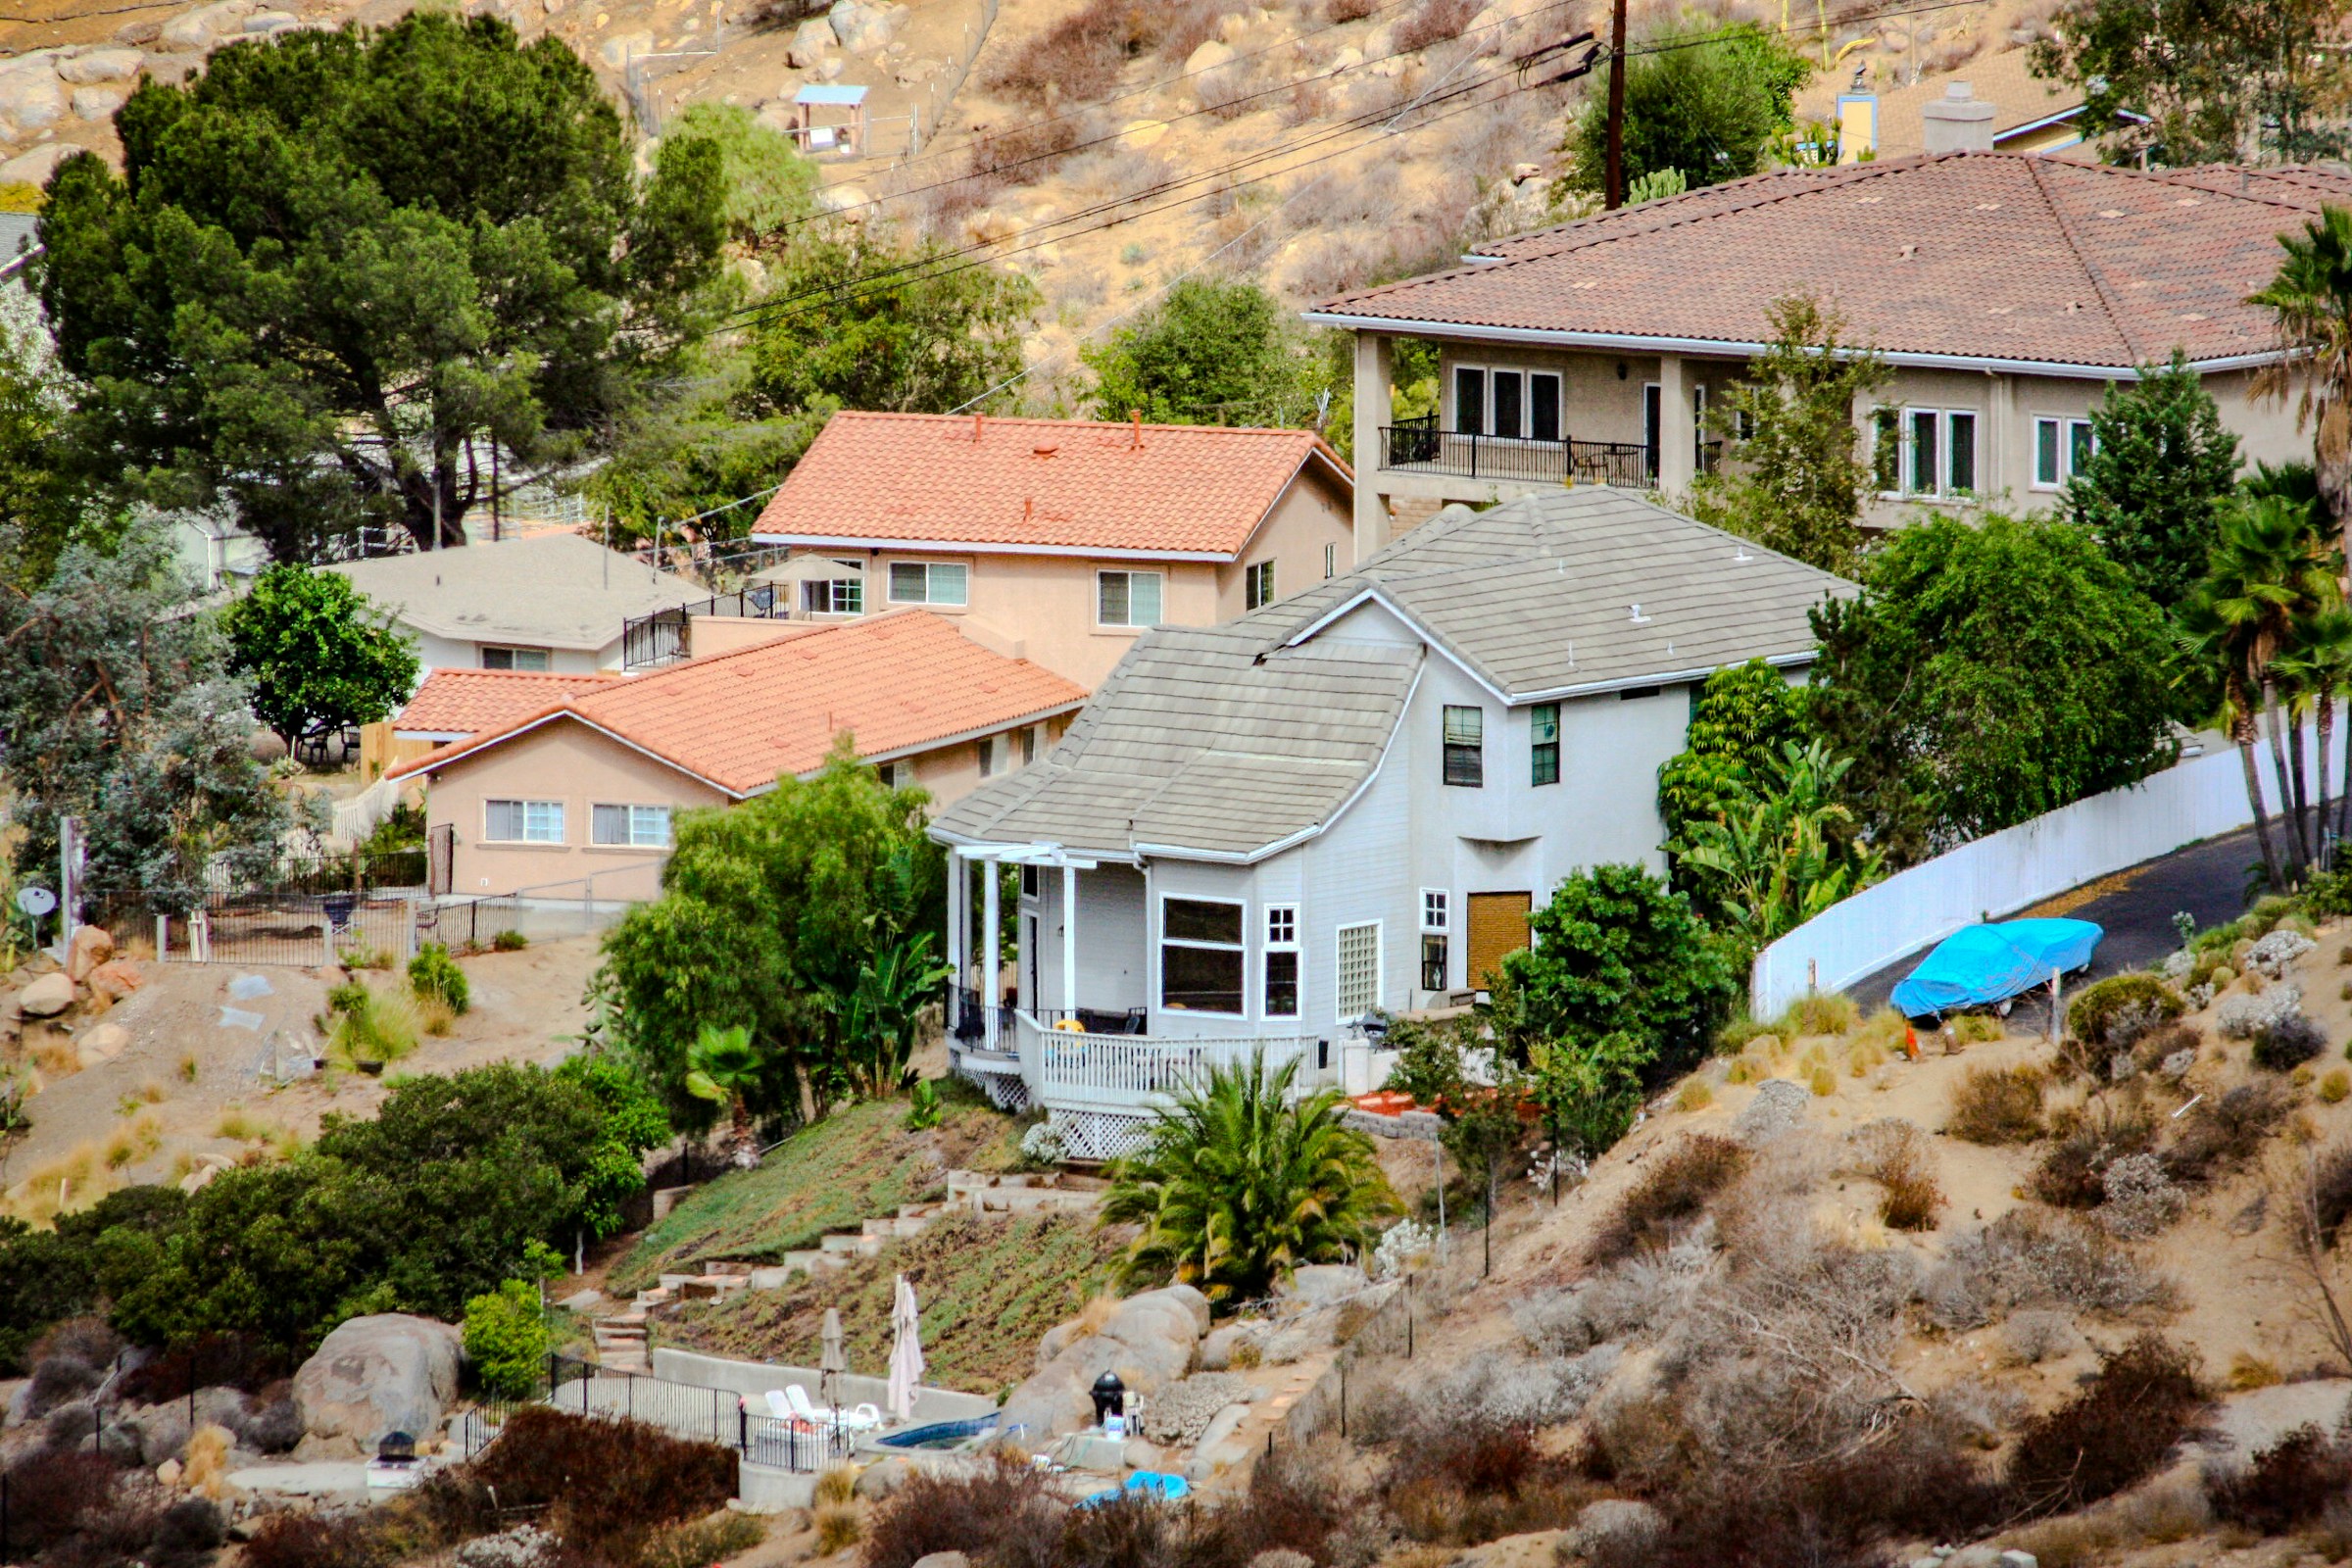
The Map Is Part of the Price
Two houses on one hillside can carry two prices because a state map line runs between them. Researchers measured the gap: about 4.3 percent on average, widening near the boundary. Then, in 2025, California redrew the maps.
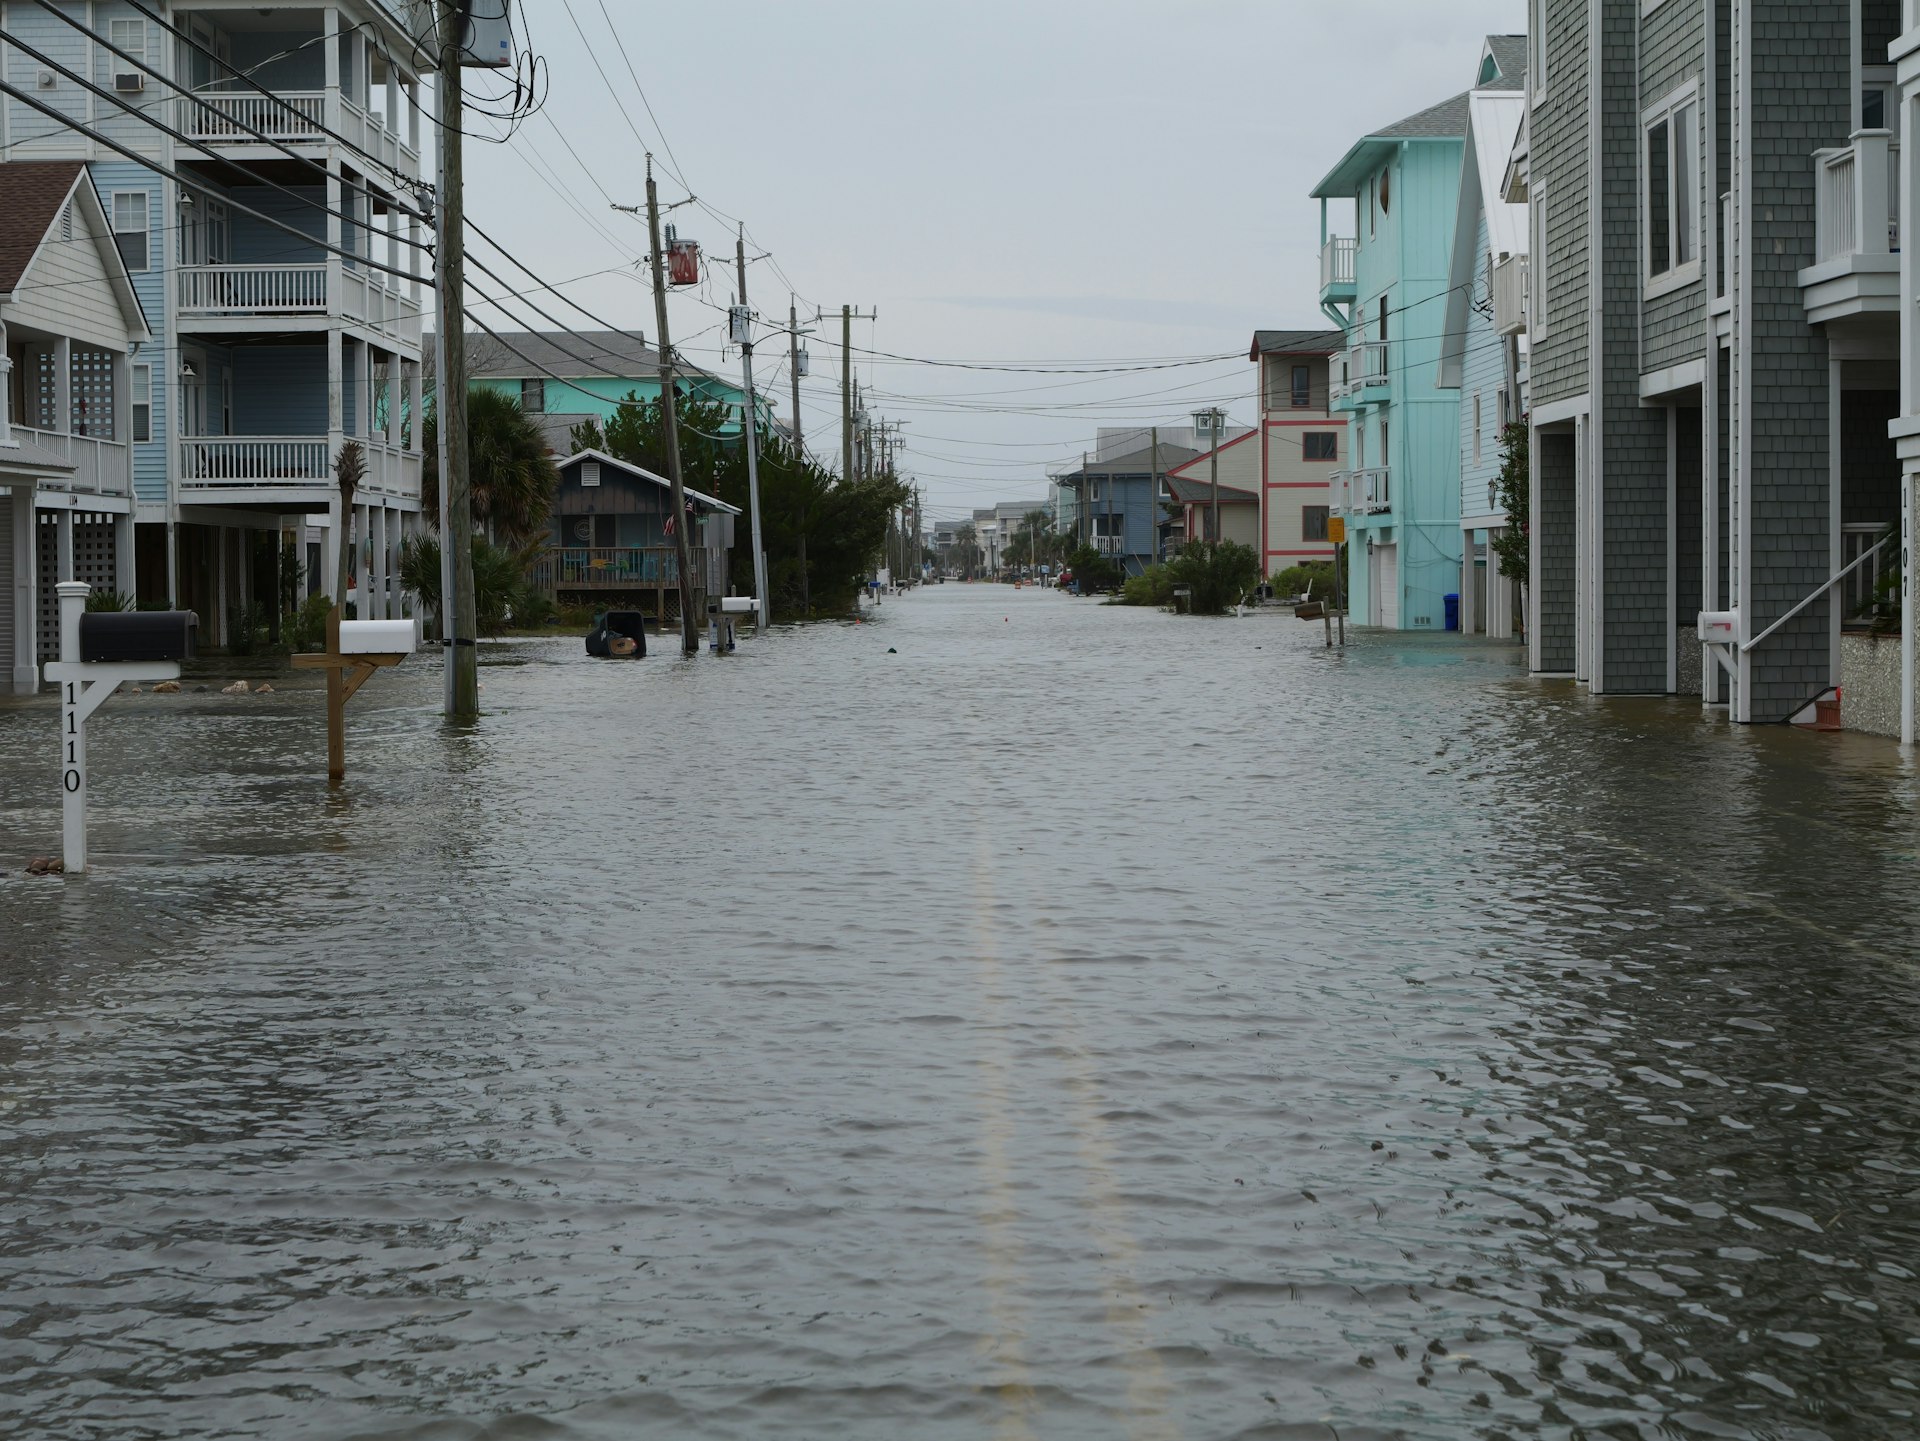
The Cost of an Honest Premium
Federal flood insurance spent decades priced below the risk it covers, with the Treasury quietly making up the difference. In 2021 FEMA started telling each home the truth about its own risk. The truth turned out to be expensive — and the people it priced hardest were the first to stop paying for protection.
What's Holding Up the Bond
There is a line on your property tax bill for voter-approved debt. It is a bond payment, collected parcel by parcel, with no reserve behind it and no revenue stream underneath it — just assessed value and the people still willing to pay on it. Which makes the credit question a question about the ground.
A “Stable” Insurance Market — Stable for Whom?
The insurers that stepped away from the fires are edging back, and the industry's grade just improved to stable. My read: that stability was purchased from homeowners — one premium hike and one non-renewal at a time.
The Tax That Makes It Expensive to Leave
You can sell a rental for less than you paid for it and still owe tens of thousands in tax. Not through any exotic provision — through the ordinary operation of depreciation. It's the cost most often left out of the decision to leave.
You Can Move Your Money to Higher Ground Without Paying Tax on the Way
Like-kind doesn't mean like-located. The code lets you exchange a rental in a fire corridor for one anywhere else in the country, and defer the tax — capital gain and depreciation recapture both. Meeting the conditions is the hard part.
You Wouldn't Put It All in One Stock. Most of Us Put It All in One Climate.
Concentration is the one risk financial advisors are trained to take seriously. Yet most households hold the majority of their net worth in a single property, on a single street, inside a single climate — and call it prudence.
Qualified Opportunity Zone Funds Require Ten Years. Spend Them on Higher Ground.
The tax break comes with a condition most people overlook: you commit to specific locations for at least ten years. And the exemption only has value if the investment actually appreciates.
Beyond the Coast: The Climate Risks Inland Buyers Overlook
Most people picture climate risk as a coastline — hurricanes and rising seas. So they buy inland and feel safe. But the risks growing fastest are landlocked, and they reprice a home the same way the water does.
Don't Let a Forever Home Put You Forever at Risk
Buying a house can be one of the most emotional financial decisions any of us make — harmless with room in the budget, dangerous when the feeling has you stretching to buy and to own a home you mean to keep forever. A story from the Berkeley hills about what emotion can hide.
The Higher-Ground Premium
Climate risk gets all the attention for what it destroys. But the same repricing that marks down the dangerous places bids up the safe ones — and that higher ground is already commanding a premium.
The Costs a Listing Won't Show You
Price, beds, square footage — a listing tells you the cost to buy. The costs that decide whether it's actually a good deal are the ones it leaves out.
Your Insurance Quote Is a Climate Forecast
When a place gets riskier, prices are the last thing to move. Insurance is the first — carriers reprice every year, and they're paid to be right about risk. Here's how to read a quote like the forecast it is.
Buy for the Long Hold: How to Spot a Climate-Resilient Market
Cap rate tells you about today. For a ten-year hold, the market's climate trajectory tells you whether today's numbers will still hold up. Here's how to read it.